Investing for Beginners: The Map Before the Money
Start with the fact that account, investment, and platform are three different things, then work through what to check before your first dollar goes in.
- Published
- 2026-09-28
- Last verified
- 2026-09-27
- Recheck by
- 2026-12-26
- Reading time
- 10 min read
- Revision
- rev.1
- Editorial approval
- Approved 2026-09-28
Co-authored and managed by John Park and his team of AI agents, orchestrated by AXE.
Investing for Beginners: The Map Before the Money
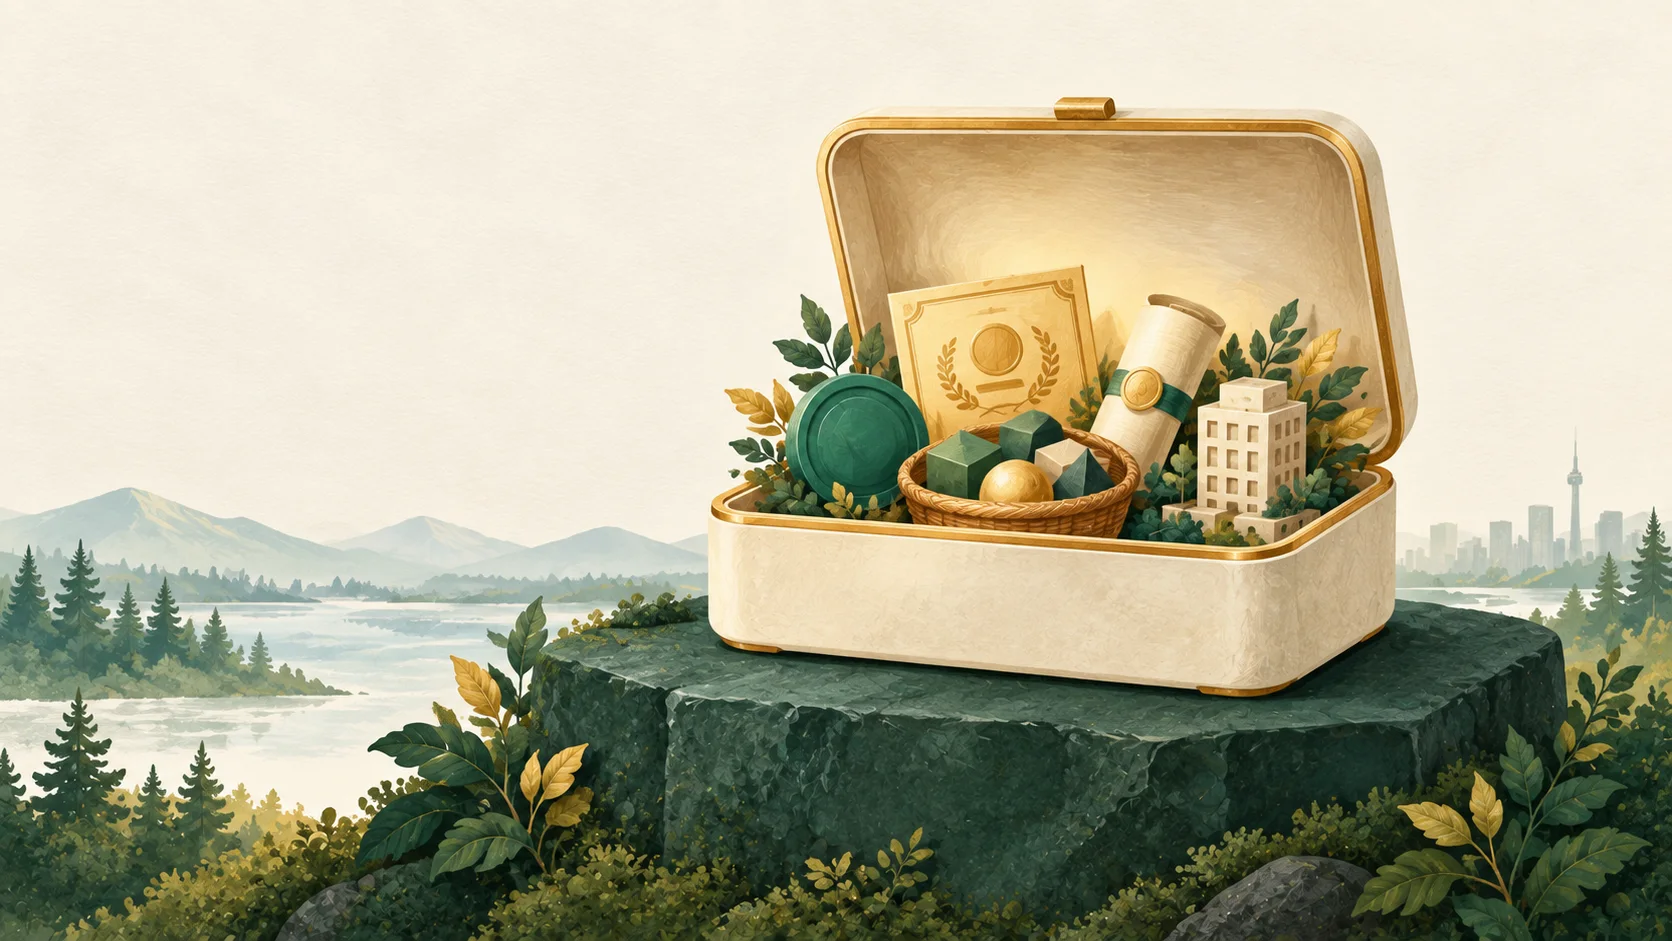 A cream container holding several different investment objects rests on a deep-green platform, showing that a platform, an account, and investments are separate layers.
Illustration 1. Platform, account, and investment are different layers. This is a conceptual illustration, not a product recommendation.
When people hear the word "investing," most immediately ask, "what should I buy?" But before that question can be answered well, you need a map. This article does not recommend any specific product. Instead, it explains the basic structure of investing and what to check before your first dollar goes in.
1. Account, investment, and platform: three different things
The most common confusion for beginners is treating these three ideas as one.
- Account is the tax-and-legal container. A TFSA or an RRSP, for example, is a framework that determines which tax rules apply to whatever sits inside it.
- Investment is the actual asset placed inside that container: cash, a GIC, a bond, a stock, an ETF, or a mutual fund.
- Platform is where and how that container is opened: a robo-adviser, a self-directed brokerage, or a bank-owned brokerage, among others.
Saying "I opened a TFSA, so now I own stocks" may not be accurate. A TFSA is only the container; if nothing has been purchased inside it, it may still just be sitting in cash. Conversely, the same stock is taxed differently depending on whether it sits inside a TFSA, an RRSP, or a regular non-registered account. Keeping account, investment, and platform separate in your head makes every later decision much easier.
2. Saving and investing are different decisions
Saving generally focuses on keeping money accessible and limiting the risk of loss. Investing means accepting the possibility of losing principal in exchange for the chance that an asset grows over time.
These two come in a sequence. Money you need within the next few months, or money set aside for emergencies, is at risk if it is put into an investment product, because the market could happen to be down exactly when you need that cash. As a general rule, short-term money is kept in savings-type instruments, and only money you can leave alone for a longer period is considered for investing.
3. Basic terms
The following terms come up repeatedly in any explanation of accounts and investments.
- Cash: money available to spend at any time. Loss-of-principal risk is low, but purchasing power can erode with inflation.
- GIC (guaranteed investment certificate): a product that runs for a set period under set conditions. Terms and any applicable deposit protection vary by product and must be checked directly.
- Bond: an asset where you lend money to a government or company in exchange for interest. There is a risk the issuer fails to honor that promise.
- Stock: partial ownership of a company. Its value rises and falls with company performance and market conditions.
- ETF (exchange-traded fund): a product that bundles multiple assets together and trades on an exchange like a stock. What each ETF holds and how it is priced varies, so it cannot be assumed that every ETF is diversified or low cost.
- Mutual fund: a product that pools money from many investors and is managed by a professional manager. How it trades and its cost structure can differ from an ETF's.
- Index: a reference point built to show the overall movement of a particular market or sector.
- Dividend: a portion of a company's profit paid out to shareholders. Not every company pays one.
- Capital gain/loss: selling an asset for more than you paid is a gain; for less, a loss.
- Risk: the possibility that the actual outcome differs from what was expected, especially the possibility that principal decreases.
- Volatility: the degree to which an asset's price moves up and down. Volatility is one type of investment risk, not the whole picture.
- Diversification: spreading money across multiple assets instead of concentrating it in one, so that a single failure is less likely to bring down the whole portfolio.
- MER/fees: the cost of running an investment product or account. Costs that look small can add up over time and reduce what you keep.
- Time horizon: when you plan to actually use the money. The shorter the horizon, the harder it is to absorb large swings.
- Compounding: the structure where returns generated by an investment are reinvested and generate further returns. The effect can grow with time, while losses reduce the base that future returns build on.
4. Canada's account containers
The Canada Revenue Agency's page on savings and pension plans introduces several kinds of registered accounts. Below is a conceptual, high-level description of what each container is for. It does not cover current limits, detailed eligibility, tax rates, withdrawal and recontribution timing, grants, deductions, or a personalized account-opening order.
- TFSA (Tax-Free Savings Account): a container designed so that growth inside it is generally not taxed.
- FHSA (First Home Savings Account): a container designed to support saving toward a first home.
- RRSP (Registered Retirement Savings Plan): a registered plan designed to help people save for retirement. Contributions and withdrawals have tax rules that need separate explanation.
- RESP (Registered Education Savings Plan): a container designed to support education savings for a child or beneficiary.
- RDSP (Registered Disability Savings Plan): a container designed to support long-term savings for a person with a disability.
- Non-registered account: a regular investment account that does not have the same special tax rules as a registered plan. Investment income and gains may need to be reported for tax purposes.
The exact limits, eligibility, and tax treatment for each account belong in separate, dedicated, tax-reviewed guides and are outside the scope of this article.
5. Platform categories and examples
Platform refers to where and how an account is opened. CIRO distinguishes self-directed (DIY) investing from advised investing, and notes that both approaches require checking the platform or adviser involved.
- Robo-advised managed investing: a service that builds a portfolio for you in an automated way based on your answers to a set of questions.
- Self-directed brokerage: the investor decides directly what and how much to buy and places the orders themselves.
- Bank-owned direct brokerage: an account opened through the brokerage arm of a bank you may already do business with.
- Working with a human adviser: managing an account in consultation with an individual adviser. CIRO advises checking an adviser's registration and background before working with them.
Examples of platform names Canadians may encounter include Wealthsimple, Questrade, Qtrade Direct Investing, Interactive Brokers Canada, Webull Canada, and various major bank-owned direct brokerages. These names are examples only, not a ranking, and this article makes no claim about their fees, features, promotions, protection coverage, or eligibility conditions. The actual terms of any platform must be verified directly with that platform and with a regulator such as CIRO.
6. Investor mindset
More important than chasing the highest expected return is building a plan you can actually stick with to the end. Markets move up and down, and it is easy to be shaken emotionally along the way. GetSmarterAboutMoney's guidance for first-time investors emphasizes setting goals first, considering diversification, and sticking to the plan.
The core of a good mindset is making decisions according to a plan set in advance rather than in the moment, not investing in anything you don't understand, and not overreacting to short-term results.
7. Risks and the strongest counterargument
Investing always carries the possibility of losing principal. The strongest counterargument to this article's "draw the map first" approach is this: "If you spend too long preparing, the growth you miss during that time is a real cost too." That argument has merit. Studying indefinitely without ever actually starting is also a form of risk.
But for that counterargument to hold, the basic conditions still need to be in place first: an emergency fund, expensive debt handled, and clear goals and time horizon. Rushing in unprepared, hitting a loss you can't handle, and giving up on investing altogether is just as common a failure as starting too late. The goal is not "perfect preparation." It is a minimum set of safeguards.
8. First-money checklist
Check the following yourself before putting money in.
- An emergency fund sized for your situation is set aside separately
- Expensive debt (such as credit card balances) is paid down, or there is a plan to do so
- You have written down why you're investing this money, along with a rough goal and time horizon
- You understand that the loss you can financially absorb (risk capacity) and the volatility you can emotionally sit through (emotional risk tolerance) can be different things
- You understand what it means to diversify instead of concentrating in one asset
- You've confirmed that fees and foreign-exchange (FX) costs accumulate over the long run
- You've built the habit of checking whether a platform or adviser is registered, for example through the OSC's check-before-you-invest resource
- You've started keeping records of transactions for future tax reporting
- You treat guaranteed returns or urgent investment opportunities from strangers with suspicion
9. What to learn next
This article is only the map. The following five short lessons will go deeper on each part.
- What investing is and is not
- Essential words you need to know
- A closer look at Canada's account containers
- Ways to invest and platform categories
- A safe first-money checklist and investor mindset
Each lesson goes further than this document, while still not recommending any specific product or account order.
Sources
- Canada Revenue Agency, "Savings and pension plans": https://www.canada.ca/en/services/taxes/savings-and-pension-plans.html
- Canada Revenue Agency, "Tax-Free Savings Account (TFSA)": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html
- Canada Revenue Agency, "First Home Savings Account (FHSA)": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html
- Canada Revenue Agency, "Registered Retirement Savings Plan (RRSP)": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans.html
- Canada Revenue Agency, "Registered Education Savings Plans (RESPs)": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html
- Canada Revenue Agency, "Registered Disability Savings Plan (RDSP)": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-disability-savings-plan-rdsp.html
- Financial Consumer Agency of Canada, "Setting savings and investment goals": https://www.canada.ca/en/financial-consumer-agency/services/savings-investments/savings-investment-goals.html
- CIRO, "DIY vs advised investing: which is right for you": https://www.ciro.ca/office-investor/investing-basics/diy-vs-advised-investing-which-right-you
- CIRO, "Selecting an adviser": https://www.ciro.ca/office-investor/investing-basics/selecting-advisor
- CIRO, "Fees and costs": https://www.ciro.ca/office-investor/investing-basics/fees-and-costs
- Ontario Securities Commission / GetSmarterAboutMoney, "Tips for first-time investors": https://www.getsmarteraboutmoney.ca/learning-path/getting-started/tips-for-first-time-investors/
- Ontario Securities Commission / GetSmarterAboutMoney, "Types of investments": https://www.getsmarteraboutmoney.ca/learning-path/getting-started/types-of-investments/
- Ontario Securities Commission / GetSmarterAboutMoney, "What is risk tolerance in investing?": https://www.getsmarteraboutmoney.ca/learning-path/understanding-risk/what-is-risk-tolerance-in-investing/
- Ontario Securities Commission, "Check before you invest": https://www.osc.ca/en/investors/check-before-you-invest
- Canada Revenue Agency, "Calculating and reporting your capital gains and losses": https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/personal-income/line-12700-capital-gains/calculating-reporting-your-capital-gains-losses.html
- Wealthsimple, "Self-directed investing": https://www.wealthsimple.com/en-ca/trade
- Questrade, "Questrade": https://www.questrade.com/
- Qtrade Direct Investing, "Qtrade Direct Investing": https://www.qtrade.ca/en/investor.html
- Interactive Brokers Canada, "Interactive Brokers Canada": https://www.interactivebrokers.ca/en/home.php
- Webull Canada, "Webull Canada": https://www.webull.ca/
Co-authored and managed by John Park and his team of AI agents, orchestrated by AXE.
Editorial gate
- Fact lock: the article uses 20 official government, regulator, investor-education, and provider pages. Provider pages establish names only. No current limits, tax rates, fee figures, guarantees, or rankings were included.
- Unresolved items: current limits, eligibility rules, and detailed tax treatment are intentionally outside this article and must be verified in separate reviewed guides.
- Native-language review: required. English phrasing and register need review before publication.
- BLOCKED_PUBLICATION: this draft cannot be published. John's explicit approval of the exact revision, legal review, tax review, and investment-professional review are not yet complete.
Sources
- canada.cahttps://www.canada.ca/en/services/taxes/savings-and-pension-plans.html
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans.html
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-disability-savings-plan-rdsp.html
- canada.cahttps://www.canada.ca/en/financial-consumer-agency/services/savings-investments/savings-investment-goals.html
- ciro.cahttps://www.ciro.ca/office-investor/investing-basics/diy-vs-advised-investing-which-right-you
- ciro.cahttps://www.ciro.ca/office-investor/investing-basics/selecting-advisor
- ciro.cahttps://www.ciro.ca/office-investor/investing-basics/fees-and-costs
- getsmarteraboutmoney.cahttps://www.getsmarteraboutmoney.ca/learning-path/getting-started/tips-for-first-time-investors/
- getsmarteraboutmoney.cahttps://www.getsmarteraboutmoney.ca/learning-path/getting-started/types-of-investments/
- getsmarteraboutmoney.cahttps://www.getsmarteraboutmoney.ca/learning-path/understanding-risk/what-is-risk-tolerance-in-investing/
- osc.cahttps://www.osc.ca/en/investors/check-before-you-invest
- canada.cahttps://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/personal-income/line-12700-capital-gains/calculating-reporting-your-capital-gains-losses.html
- wealthsimple.comhttps://www.wealthsimple.com/en-ca/trade
- questrade.comhttps://www.questrade.com/
- qtrade.cahttps://www.qtrade.ca/en/investor.html
- interactivebrokers.cahttps://www.interactivebrokers.ca/en/home.php
- webull.cahttps://www.webull.ca/
Korean original
Read the Korean original at /articles/investing-for-beginners-map-before-money-ko →